MKTMarketsMarket close NO. ---
US stocks brief: Dow up 1%, tech stalls before Tesla and Meta
The Dow and small caps rallied on October 20 as money rotated out of megacap tech, yields eased and oil slipped from a five-month high. We look at the drivers, the Fed and midterm backdrop, and the calendar ahead of Tesla and Meta results.

Data as of: US close, 4:00 p.m. ET (20:00 UTC), Tuesday, October 20, 2026; after-hours quotes around 5:10 p.m. ET; overnight indications as reported by about 02:30 UTC, Wednesday, October 21. Treasury yields are official end-of-day par yields.
Key takeaways
- The Dow Jones Industrial Average rose 1.02% to 52,495.88 on October 20. The S&P 500 gained 0.28% to 7,712.57, and the Nasdaq Composite was flat at 26,424.82. The Russell 2000 led with a 1.65% gain.
- Money rotated out of megacap technology and into health care, financials, real estate and small caps. An equal-weight S&P 500 fund rose 1.15%, about four times the gain in the cap-weighted index.
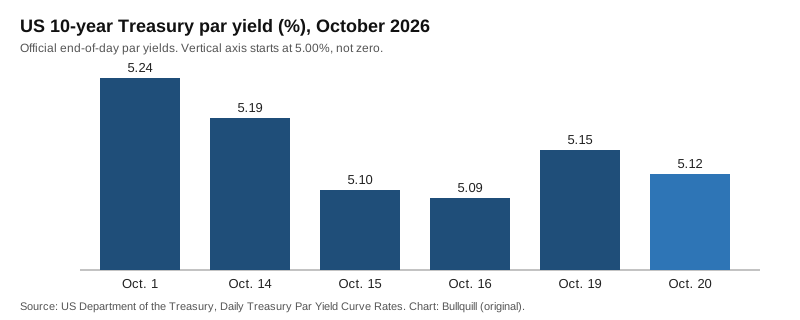
- The 10-year Treasury yield eased to 5.12% while the 2-year rose to 4.79%. Oil slipped after touching a five-month high.
- Politics is close to the surface. The November 3 midterm elections are two weeks away, President Trump has said the US will not strike Iran before the vote, and tariff policy is still being rebuilt after this year's Supreme Court ruling.
- Next: Tesla, Meta and IBM report after Wednesday's close, and the Federal Reserve announces its decision on October 28.
Session recap
| Index | Close | Change (points) | Change (%) |
|---|---|---|---|
| Dow Jones Industrial Average | 52,495.88 | +529.85 | +1.02% |
| S&P 500 | 7,712.57 | +21.84 | +0.28% |
| Nasdaq Composite | 26,424.82 | -6.07 | -0.02% |
| Russell 2000 | 2,773.41 | +45.12 | +1.65% |
| Philadelphia Semiconductor Index | 11,283.81 | n/a | -0.29% |
| Cboe Volatility Index (VIX) | 17.31–17.44 | about -1.0 | -5.4% to -6.1% |
Sources: Capp Notes and Vista Global closing recaps, October 20, 2026. The two agree on the main index closes; their VIX readings differ slightly, so a range is shown.
| Measure | Level | Daily change | Source |
|---|---|---|---|
| 2-year Treasury par yield | 4.79% | +0.02 pt | US Treasury |
| 10-year Treasury par yield | 5.12% | -0.03 pt | US Treasury |
| 10-year real (inflation-indexed) yield | 2.77% | -0.03 pt | US Treasury |
| Brent crude, December (settlement) | $108.79 | -0.69% | Reuters via Yahoo Finance |
| US Dollar Index (DXY) | 101.71 | -0.26% | Capp Notes |
Breadth was strong: Capp Notes counted 1,614 advancing NYSE issues against 559 decliners. In evening trading, Trading Economics reported Nasdaq 100 futures up about 0.7%. Futures indications can change before the open.
What drove it
Earnings and deals
According to Vista Global, 3M beat earnings forecasts ($2.50 a share against $2.38) and raised its outlook; the stock rose about 5.8%. Northrop Grumman gained 4.57% after a beat. General Motors topped forecasts but narrowed its profit outlook and fell about 7%. Braze jumped about 52% on a pending $47.50-a-share cash offer from Salesforce. After the bell, SpaceX reported revenue up 161% to $14.58 billion and rose in extended trading, while Netflix fell about 5.7%, per Capp Notes.
Macro data and the Fed
September housing starts fell 5.2%, and pending home sales hit a record low in data going back to 2001, Vista Global reported. Inflation is the bigger constraint: the Bureau of Labor Statistics said consumer prices rose 3.7% in the year to September, with energy up 20.4%.
The Fed raised its target range to 3.75%–4.00% on September 16, saying “Inflation remains elevated.” For October 27–28, Kalshi priced an 87% chance of a hold and CME FedWatch about 14.9% odds of a hike, per Capp Notes. Another hike by year-end was priced at roughly 85% to 90%, according to Reuters and FXStreet. These are market estimates, not decisions.
Geopolitics and oil
Brent touched $111.99 a barrel, a five-month high, then settled lower, Reuters reported. Kpler counted at least 18 vessels attacked in two weeks around the Strait of Hormuz. Unconfirmed reports of a Qatar–Pakistan mediation proposal pulled prices back, though a US diplomat called reports of an imminent deal inaccurate, per Capp Notes. Softer long-term yields helped rate-sensitive sectors.
Flows and sentiment
Technology was the only sector to fall. Lam Research lost 3.21% and Arm 3.07%, per Capp Notes, amid concern about how the AI build-out is financed. Analysis: an equal-weight index beating the cap-weighted one by this much suggests money spreading across the market. One day does not make a trend.
Political & policy watch
- Midterm elections, November 3. Control of Congress, and with it tax, spending and regulation, is at stake. On October 8, President Trump posted: “We will not be attacking Iran at any time prior to the midterm elections,” Al Jazeera reported. Some analysts saw it partly as an attempt to cool oil prices.
- Tariffs. After the Supreme Court struck down the IEEPA tariffs on February 20, a temporary Section 122 tariff expired on July 24 and was replaced by Section 301 tariffs of 10% or 12.5% on 60 economies, according to the Penn Wharton Budget Model. It puts the effective tariff rate at 7.1% in August, against 2.3% in January 2025, and says about $126 billion of IEEPA refunds had been certified by October 2.
- The Fed. Remarks by Chair Kevin Warsh did little to change expectations of an October hold, Reuters reported. His October 28 press conference is the next scheduled guidance.
What it means
Analysis. The market is weighing earnings that mostly beat forecasts against a Fed that is still tightening and an oil price driven by war and diplomacy. The Fed meeting and the midterms could shift all three within two weeks.
Next session: our US stocks brief for October 22 covers how the Nasdaq sank 2.6% on AI costs. For the detail behind that drop, see why AI spending worries pushed the Nasdaq down to 26,008.86, how Meta's credit default swaps hit a record as AI spending leaned on debt, and why Moderna and Merck shares fell on early melanoma vaccine data. New to the instrument? See credit default swaps explained.
What to watch next
- Wednesday, October 21, before the open: Abbott, NextEra Energy, AT&T, Thermo Fisher, Danaher, Philip Morris, Elevance Health, CME Group and Moody's (schedule per Capp Notes).
- Wednesday, 10:30 a.m. ET: EIA weekly crude inventories.
- Wednesday, after the close: Tesla, Meta, IBM, Lam Research, Texas Instruments and SAP. Meta's call is at 4:30 p.m. ET and Tesla's webcast at 5:30 p.m. ET.
- Thursday, October 22, 8:30 a.m. ET: initial jobless claims (consensus 200,000, prior 199,000, per TD Economics).
- Friday, October 23, 9:45 a.m. ET: S&P Global flash PMIs for October.
- October 27–28: FOMC meeting; decision and press conference on October 28.
- November 3: US midterm elections. November 10: October CPI.
Risk checklist for readers
- Index versus average stock. Compare cap-weighted and equal-weight measures; a flat headline index can hide large moves underneath.
- After-hours moves are provisional. Extended trading is thin, and prices often change by the next open.
- Event risk is clustered. Big-tech earnings, the Fed, the midterms and Iran headlines all fall within two weeks, which can raise volatility.
- Probabilities are not decisions. FedWatch and prediction-market odds move with each data point.
- Check timestamps. Sources capture prices at different times; small differences between reports are normal.
Frequently asked questions
How did US stocks close on October 20, 2026?
The Dow Jones Industrial Average rose 529.85 points (1.02%) to 52,495.88, the S&P 500 gained 0.28% to 7,712.57, the Nasdaq Composite slipped 0.02% to 26,424.82, and the Russell 2000 rose 1.65%, according to Capp Notes and Vista Global.
What are markets expecting from the Fed on October 28?
Market gauges cited by Capp Notes priced a hold as most likely (Kalshi 87% hold; CME FedWatch about 14.9% hike odds). Another hike by year-end was priced at roughly 85% to 90%. These are market estimates, not Fed decisions.
Why do the midterm elections matter for US stocks?
The November 3 vote decides control of Congress, which shapes tax, spending, tariff and regulatory policy. President Trump has also said the US will not strike Iran before the vote, which markets watch because of its link to oil prices.
Is this brief a recommendation to buy or sell US stocks?
No. It explains what happened and why, using published data. It does not recommend any security, strategy or price level and is not investment advice.
Sources
- Capp Notes: Closing Look, Tuesday, October 20, 2026
- Vista Global: Stock Market Today, October 20, 2026
- US Treasury: Daily Par Yield Curve Rates, October 2026
- US Treasury: Daily Real Yield Curve Rates, October 2026
- Reuters via Yahoo Finance: Brent falls as Iran's president discusses mediation (Oct. 20, 2026)
- Trading Economics: US stock market news and futures
- Bureau of Labor Statistics: Consumer Price Index, September 2026
- Federal Reserve: FOMC statement, September 16, 2026
- Reuters via Investing.com: Fed outlook and Warsh comments (Oct. 20, 2026)
- FXStreet: Rate-hike pricing citing Prime Terminal (Oct. 20, 2026)
- Al Jazeera: Trump says US will not strike Iran before midterm elections
- Penn Wharton Budget Model: Effective tariff rates and revenues, October 14, 2026
- TD Economics: Upcoming economic releases, week of October 19
Risk warning: Stocks are high-risk. Their value can fall, and you could lose some or all of the money you invest. Do your own analysis, and bear in mind that no product is suitable for everyone. Past performance does not guarantee future results.
This article is for information only and is not investment advice.


